
Are Japan’s asset owners ditching US Treasuries?
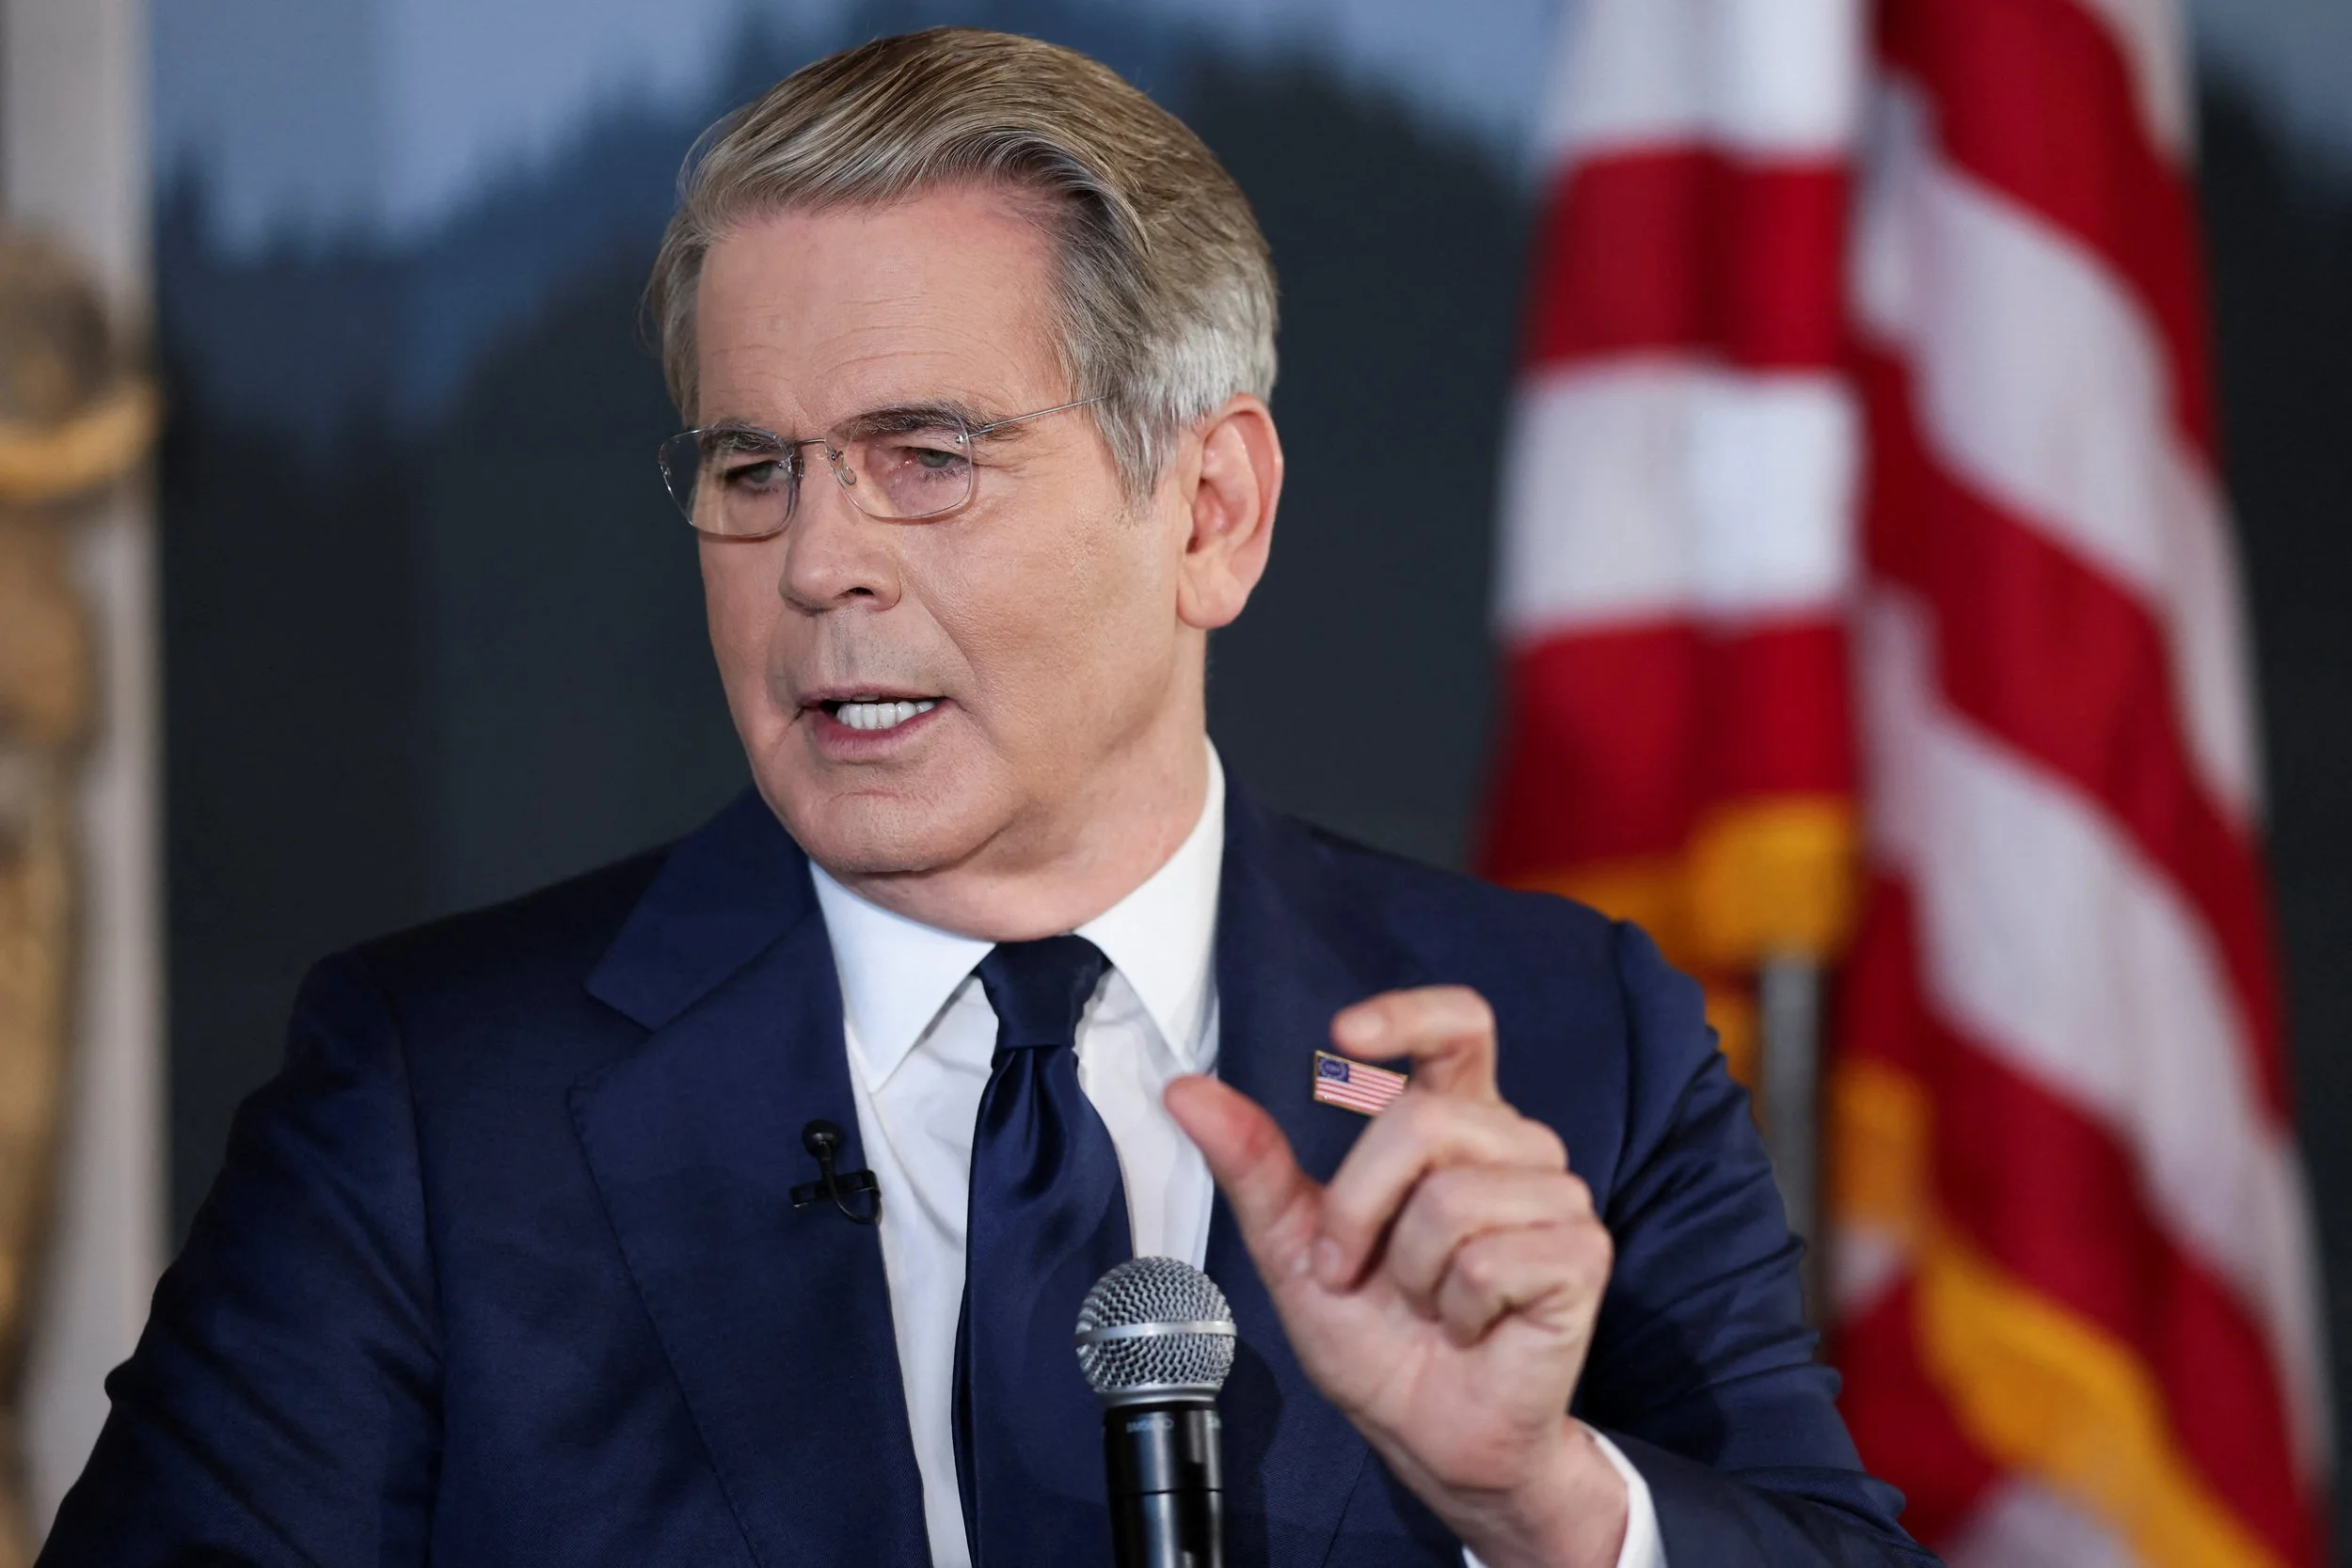
Treasury secretary Scott Bessent has been intervening in the market to strengthen the yen - in a bid to discourage Japan’s investors from selling dollar assets such as US government bonds. We speak to asset owners to find out if he’s right to be concerned (Sam Wolfe/Reuters)
As US Treasury secretary Scott Bessent applies unusually direct pressure on the Bank of Japan to raise interest rates, rising domestic yields are reviving Japanese asset owners' appetite for domestic government bonds – or JGBs – which are attractive again after nearly a decade of near-zero rates.
In recent weeks Bessent has made a series of pointed remarks urging the BoJ toward tighter policy. For US policymakers a narrower rate gap, driven by BoJ hikes, offers a gradual path to yen strength.
A weak yen means Japan may have to sell dollar assets such as US Treasuries to support its own currency.
This matters because Japan is the largest foreign holder of US Treasuries so it risks spiking US borrowing costs if that same shift toward domestic bonds prompts a sudden pullback from its US holdings.
Earlier this month the BoJ decided to raise interest rates by 25 basis points, taking its benchmark policy rate to around 1.25 per cent. This comes after the US Federal Reserve raised its federal funds rate by 25 basis points to a target range of 3.75–4 per cent.
BoJ Governor Kazuo Ueda noted that the central bank would keep raising rates as underlying inflation nears 2 per cent and conditions remain accommodative, with the timing and pace of further hikes hinging on Middle East tensions, AI-driven demand, and currency moves.
The move marks a reversal from 2016, when the Abe administration's aggressive monetary easing — including the BoJ's introduction of negative interest rates -- drove Japanese asset owners away from domestic bonds.
So what do they make of the most recent moves? And is the US Treasury right to be concerned that Japan’s asset owners might swap Treasuries for JGBs?
Unlike vocal overseas peers such as Norway’s $2.3tn Government Pension Fund, which announced a massive cut to its US Treasury holdings, Japanese asset owners have been relatively prudent so far.
But a gradual rebalancing toward domestic bonds is expected as yields become meaningfully more attractive.
Japan Post Insurance, which manages $382bn, plans to proactively allocate to domestic bonds over the coming three-year term, in addition to other income-generating assets such as global infrastructure and domestic property.
"Given an attractive interest rate environment that exceeds our cost of liabilities, we will step up both portfolio replacement and new investment in domestic bonds, covering the medium- to long-term zone in addition to the super-long-term zone," Naoki Hashimoto, a specialist at the lifer's investment planning department tells AOX.
The lifer expects its offshore bond exposure, more than 60 per cent of which is US-denominated, to decline because its attractiveness has diminished amid rising domestic rates. This particularly applies to hedged assets, where hedging costs increasingly eat into yields as the US-Japan rate differential narrows.
"At the same time, should a sudden financial crisis occur, interest rates would likely decline. While we plan to reduce our overall foreign bond holdings, we will continue to maintain a certain level of exposure while selectively rotating and rebalancing the portfolio," he added.
Naoya Sugimoto, co-chief investment officer at Japan Science and Technology Agency, which oversees a $78.1bn fund which launched in 2022, tells AOX that dollar-denominated assets inevitably make up the largest share simply because of the size of the US market.
"As we are still in the portfolio construction phase we continue to build the portfolio steadily and methodically. So rather than selling US assets drastically and shifting into other regions due to the mounting uncertainty, we will essentially adjust the existing portfolio incrementally, as circumstances warrant," Sugimoto said.
Much attention is focused on the $2tn Government Pension Investment Fund, which revealed last month an unexpected portfolio review – despite telling AOX in July that no immediate review was needed.
The fund usually reviews its portfolio every five years – and the last one was completed last year, when it decided to maintain its target allocation. As AOX recently covered, the fund is facing pressure from Japan’s government to increase investment in its domestic economy.
Kenji Shiomura, a fellow at the Daiwa Institute of Research, said GPIF's executive is unlikely to unilaterally raise its domestic bond weighting within the existing tolerance band.
The fund has a target allocation to domestic bonds of 25 per cent – with a tolerance of six percentage points either side. Its target allocation to foreign bonds is also 25 per cent but with a tolerance of five percentage points.
As of June 2026, GPIF had an allocation of 25.59 per cent to domestic bonds and of 24.6 per cent to foreign bonds.
Still, given the recent rise in domestic interest rates — and the possibility of further increases — Shiomura said it cannot be ruled out that GPIF has, in fact, taken a real step toward reviewing its policy portfolio. It's also possible, he added, that the goal was simply to document that a review had been considered without any intention of acting.
Shiomura said that if the board reaches informal agreement on a review, GPIF could quietly increase its domestic bond allocation beforehand, only formally announcing the change once the shift is complete.
Two upcoming disclosures could offer early clues, Shiomura said: GPIF's next board agenda, expected by early October, may show whether the portfolio review reappears on the agenda, while its second-quarter investment results, due in early November, would reveal whether asset weights have already drifted from the 25 per cent target. That, he said, would signal a shift is already under way.