
How this Canadian university fund learnt to box with the Maple Eight
University of British Columbia Investment Management, which is responsible for about $5.4bn in pension and endowment assets, has figured out how to access opportunities which its scale might not otherwise allow it (Chris Helgren/Reuters)
In institutional investing conventional thinking has long held that scale confers advantage.
And for good reason. Larger investors have more negotiating power, greater resources, access and the capacity to build in-house investment capabilities across the globe.
They can write more substantial cheques, be more precise in portfolio construction, obtain more favourable fees and devote departments to individual strategies.
But Dawn Jia, president and chief executive of University of British Columbia Investment Management, responsible for about $5.4bn in pension, endowment and other assets, believes scale is not the only factor involved in generating investment returns.
A former portfolio manager at the $598bn Canada Pension Plan Investment Board, UBCIM’s chief is extremely familiar with the benefits that scale can bestow.
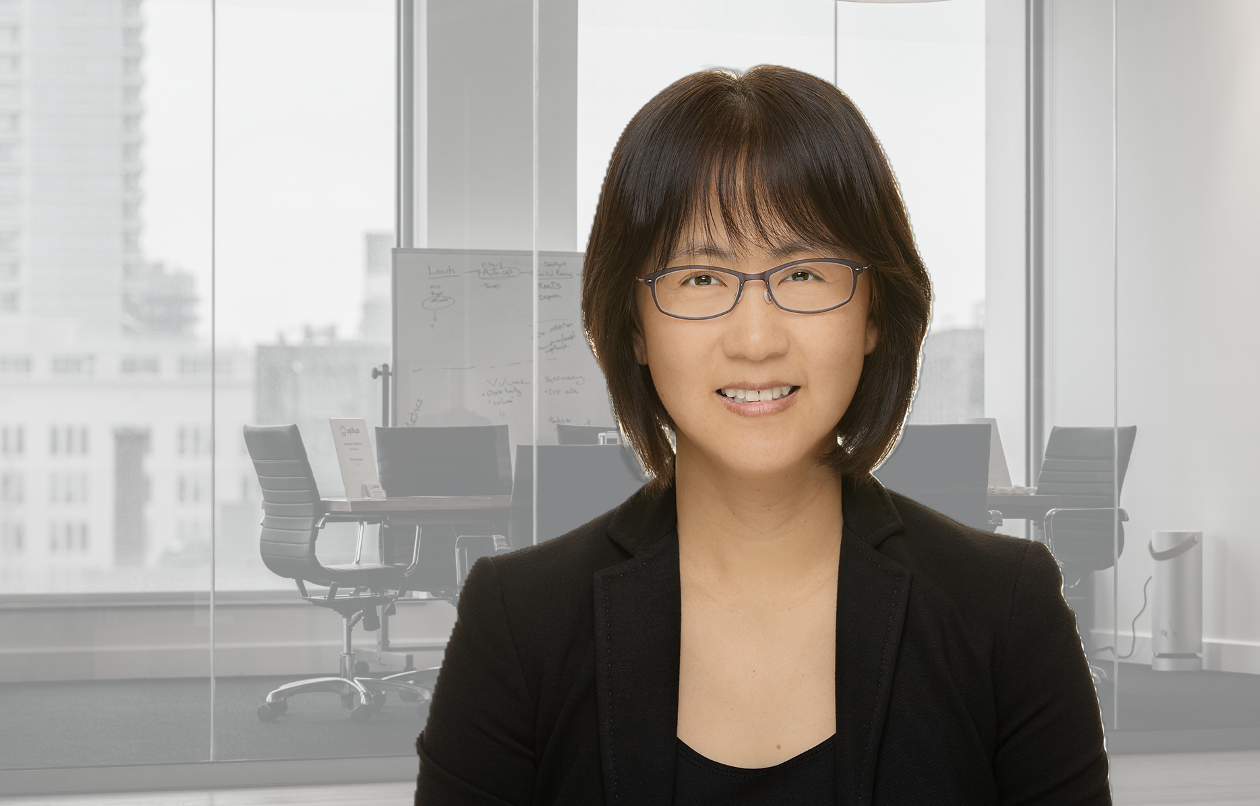
Dawn Jia, president and chief executive of University of British Columbia Investment Management, used to be a portfolio manager at the $598bn Canada Pension Plan
“Capital is king,” Jia concedes. “You definitely have the bargaining power, whatever you do.”
But since taking the helm of UBCIM in 2019, Jia tells AOX she believes much of its recent investment performance has been driven from operating in a way that may be harder for the largest asset owners to replicate.
So it goes that while scale can be an advantage, it can also become a constraint – and smaller institutions can deliberately design around it.
Namely by operating a business model that grants the abilities to move quickly, work with niche partners on smaller opportunities and carve out unique co-investment structures.
As part of an internal review, two years ago UBCIM began comparing its performance data at the asset class level to publicly available information from the Maple Eight, Canada’s largest pension investors.
While Jia recognises that direct comparisons are imperfect given varying risk tolerances, fiscal dates and mandates between investors, she felt there was still information to be gained from analysing returns by asset class.
Over the period it studied, UBCIM’s performance records indicate that its returns were higher than the comparable publicly-available Maple Eight data in a majority of asset classes it tracked.
Jia attributes that outcome to several factors but one common thread is how UBCIM, whose investments are 100 per cent externally managed, has chosen to deploy its resources.
She sees its manager-of-managers approach as an advantage rather than a limitation, describing its benefits in three words: diversification, efficiency and agility.
“Diversification in the sense that you can work with so many localised, niche strategies across geographies and sub-asset classes,” she said.
Efficiency and agility mean both quick access to alpha and beta exposure without the hindrance of having to develop an internal team as well as the speed to move in and out quickly.
“If a new investment opportunity emerges from the market, you can get in quickly.”
Less crowded markets
That flexibility has shaped how and where in the private markets UBCIM chooses to invest.
Over the four years since 2022, the allocation to private equity within UBC’s endowment fund has gone up from 8.4 per cent to 11.9 per cent.
“Most of our private asset classes are playing in the lower mid-market segment. It is a larger segment, but less crowded, less competitive and more attractively priced,” Jia explained.
She added that the arena for smaller to mid-sized assets has been less plagued by the sluggish exit environment the larger end of the market has experienced in recent years.
“Where we play and how we play is one of the key reasons for the higher return.”
Rethinking co-investment
While asset owners often covet co-investment opportunities, many lack the required internal capacity or bargaining power.
Recognising this reality, Jia told her board there should be no deal-by-deal co-investments in the first few years, explaining: “We need to work purely in the fund space given team resources. Once we get to a certain scale, and once our team builds the in-depth asset class knowledge, then we will get into deal-by-deal co-investment.”
But UBCIM was able to arrange so-called “passive co-investment opportunities” that it organised specifically with its managers.
That approach has allowed UBCIM to reap some of the economic rewards of co-investment, including, in many cases, no-fee no-carry arrangements without needing to replicate the investment capacity of its managers. This has been especially lucrative for lifting private market returns, where large portions typically go to fees and carry.
To negotiate special co-investment structures, investors need to show they are at the same knowledge level as their managers in terms of market knowledge, deal knowledge and product knowledge, she explained.
In other words, treat GPs as partners rather than vendors.
“Today, when we do co-investments, the managers will do the majority of the work and we’ll set certain parameters based on our program design and construction.”
“When a deal fits those parameters, we are in,” she explains.
For other asset owners who may need to get creative when entering the co-investment space, Jia offers the following advice: “Come up with new structuring ideas and discuss them with your manager. We’ve done that across many of our investment activities beyond co-investment – even when deals require restructuring, we’ve been creative. Our managers love that, because we are helping solve problems.”
Simply put, investors can gain access by being useful, not just purchase it through size.
The case against internalising by default
While large asset owners have greater resources, they are far from unlimited. An investment department of 100 or 200 people still has a finite capacity; smaller transactions may struggle to justify the time and resources required to underwrite them.
“If it’s lower than $100mn or $200mn, you almost wonder, is it worth it for my team to work on?,” she asks, noting that the deal size may not be economically compelling for the largest pools of capital.
Geography creates another constraint. “On the private side, you always need localised relationships and information,” she said. There is a difference between global presence and geographic intimacy.
There are also behavioural considerations at play. Overconfidence is a common bias Jia has seen throughout her career.
“When people make the decision of internal versus external management, they may be subject to that bias, thinking that they can build a top quartile team internally,” she says, comparing it to research that finds most drivers believe they have above-average driving ability.
But specialist external managers may have spent decades developing experience in a particular market or niche. “We should respect that expertise, especially that localised expertise, those niche players.”
That does not mean external management is better in all cases. More importantly, it means an asset owner’s scale shouldn’t make the decision automatically. For larger institutions, this can mean resisting the notion that internalisation is inherently better.
Asset owners should return “back to first principles” and evaluate their own capabilities, what the investment opportunity requires and what investment structure will produce the highest net return.
For larger asset owners, that may be the more interesting lesson from UBCIM’s experience - that comfort in size can risk putting certain decisions on autopilot
Jia points out that sometimes, deploying your resources most effectively may mean not trying to build everything in-house.
For smaller asset owners, there is also an encouraging lesson.
While they may not be able to compete with larger institutions on resources or bargaining power, they can compete on focus, relationships and speed, and the ability to pursue smaller opportunities that are beneath the radar of the largest investors.
Taken together, these components can help close the gap in comparative advantage scale provides.