
How are South Africa’s pension funds handling their domestic market’s concentration?
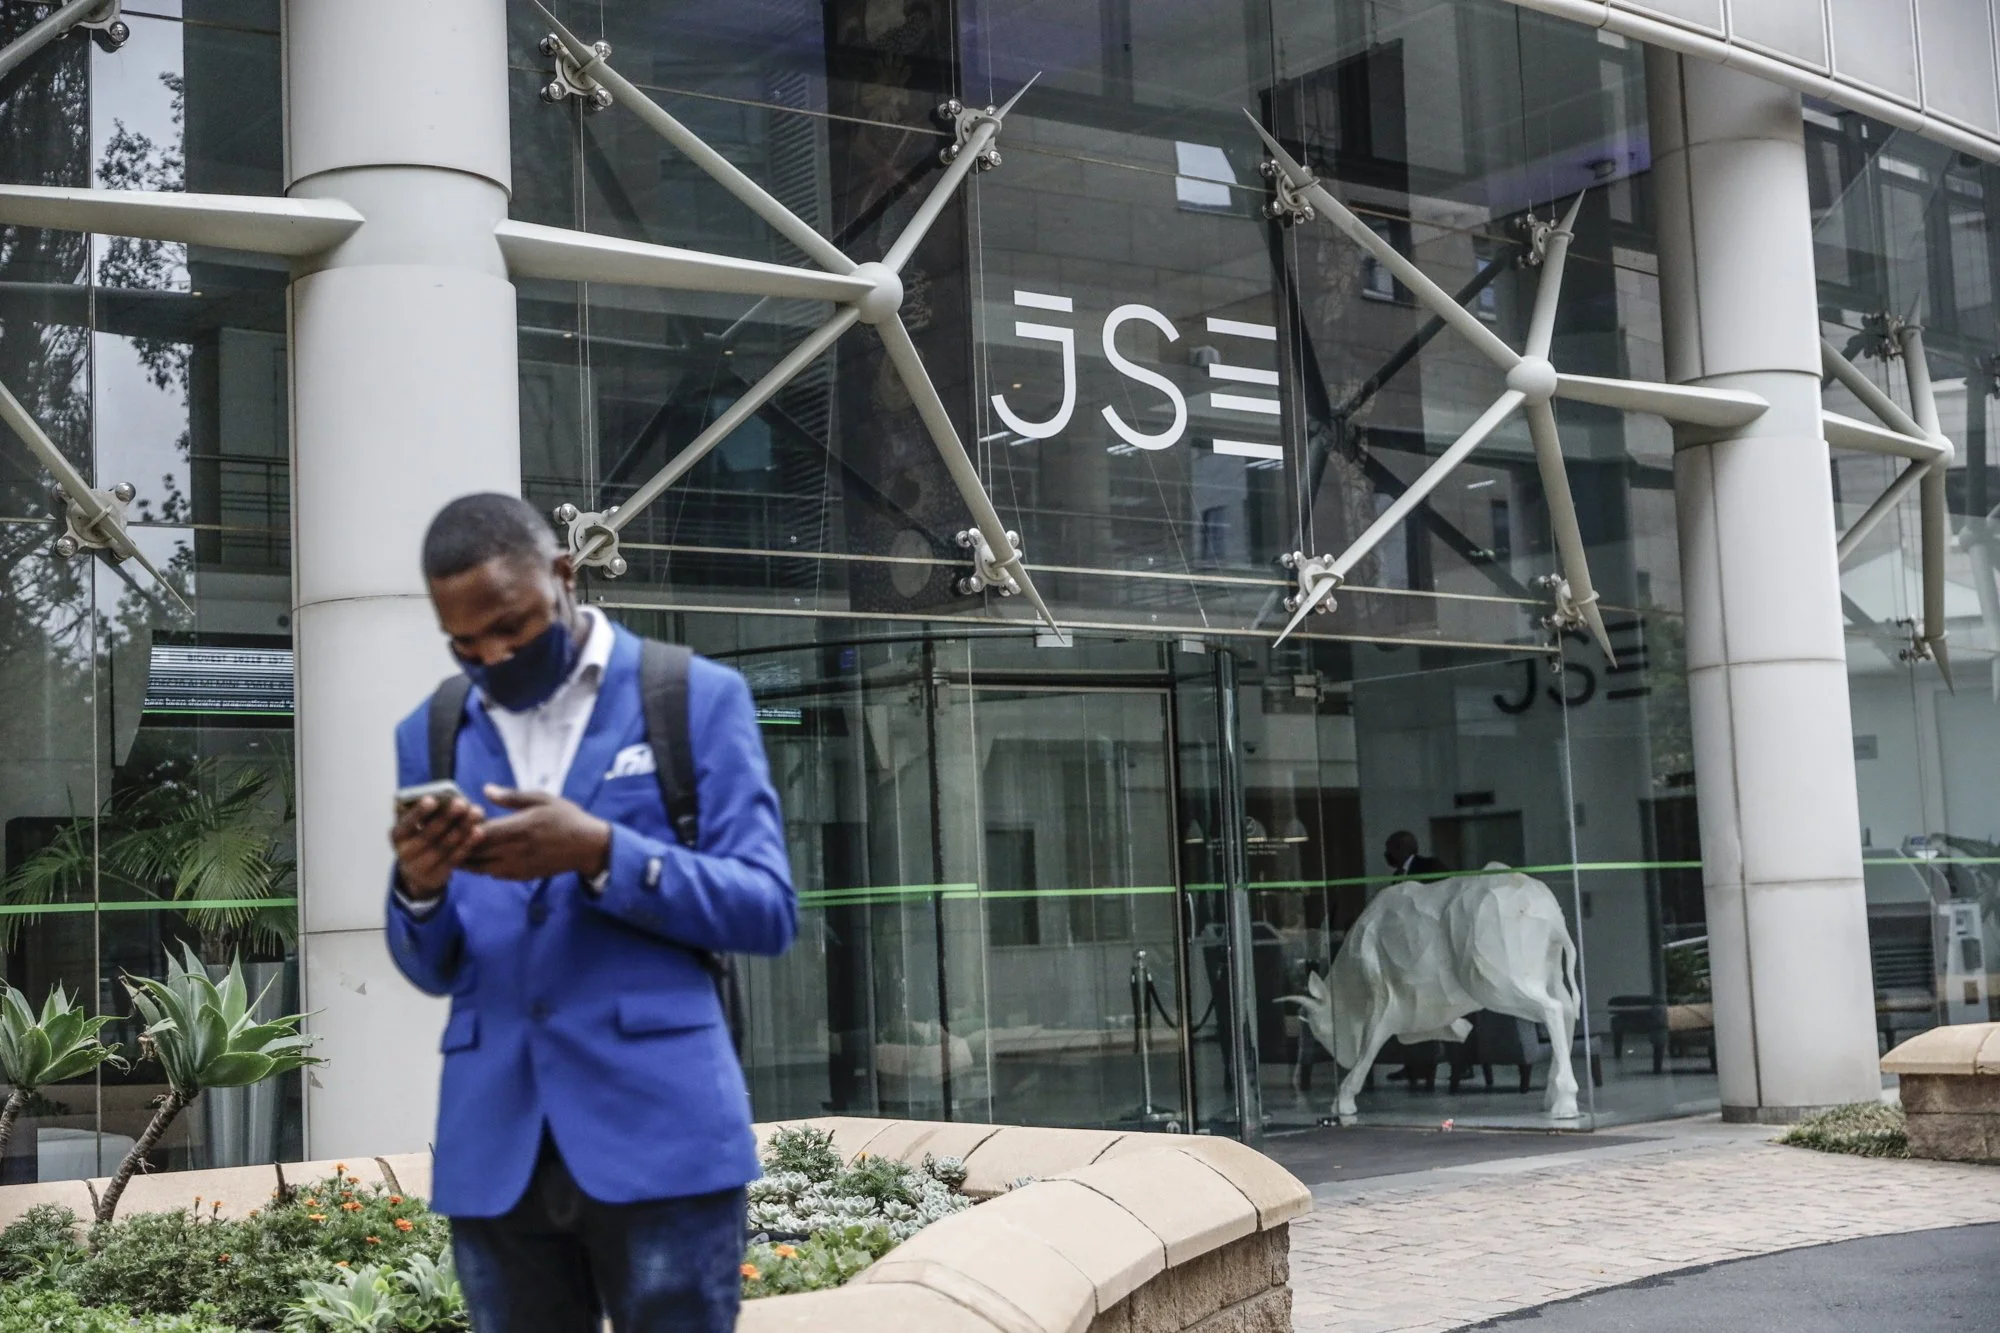
South Africa’s pension funds are required to invest more than half their assets in their domestic market, but over the past 10 years the number of listings on the Johannesburg Stock Exchange has fallen by half. How are they addressing this? (Guillem Sartorio/AFP/Getty Images)
When investors think about concentration risk, it is generally within the context of tech companies and their dominance of the US market.
But the shrinking number of listings on the Johannesburg Stock Exchange has been giving South Africa’s pension funds plenty to think about – particularly given they are required to invest at least 55 per cent of their assets domestically.
Listings on the JSE have nearly halved in the past 10 years, largely driven by mergers and acquisitions, such as the acquisition of Imperial by DP World and Royal Bafokeng by Impala Platinum.
But companies have also sought primary listings abroad, such as Prosus, which moved its primary listing to the Netherlands.
Monika Kraushaar, head of investment advisory at RisCura, tells Asset Owner Exchange that a few larger companies now dominate the JSE by market capitalisation but, she said, they do not dominate the investable universe for South African pension funds.
Monika Kraushaar of RisCura says while concentration in the South African market is high, diversification is available
“These companies often do not appear in the top 10 when measured by weight in a capped All Share Index, creating a distinction between total market cap and actual investment portfolio composition,” Kraushaar said.
Over the past 20 years, the JSE has addressed concentration issues by launching Shareholder Weighted Index, weighting companies by shares which were actually registered in South Africa. This was later upgraded to Capped SWIX which restricts a company’s weight to a set level.
Simon Brown, investment specialist at Just One Lap, said the All Share Index failed to reflect the true, investable domestic market for asset managers.
“Pension funds generally prefer capped indices to limit single-stock exposure, with current indices capped at 12 per cent to prevent the concentration risks seen in previous years,” Kraushaar added.
Historically tech company Naspers and its subsidiary Prosus together accounted for approximately 23 per cent of the JSE Shareholder Weighted Index.
Equal-weighted indices are much less common because of the high costs of constant rebalancing and the liquidity issues involved in forcing allocations to smaller-cap shares, she noted.
The JSE also exhibits a high level of concentration risk in specific sectors, with financial services accounting for approximately 18 to 19 per cent, commodities for roughly 28 per cent, and the Naspers and Prosus combination for about 10 per cent, which together make up roughly 57 per cent, Kraushaar noted.
“Although sector concentration is high, there is inherent diversification within those sectors,” she said.
Within the commodities sector, producers of gold, platinum, coal and iron ore each respond differently to cyclical market forces, helping to mitigate risk.
To diversify, South African pension funds are using a combination of active and passive strategies, she said.
“Passive strategies tie investors to benchmark weights, such as the commodity exposure in the capped index, whereas active managers have the discretion to overweight, underweight, or avoid specific shares entirely based on their market outlook,” Kraushaar said.
Diversification is also achieved by mixing larger asset managers – who may be restricted by liquidity when investing in mid- or small-cap stocks – with smaller managers who can hold meaningful positions in these companies.
Pension funds also mitigate some risk by diversifying both offshore and domestically across sectors, but the JSE is highly sensitive to the South African rand.
The market is split between "rand hedge" stocks which benefit from a weaker rand – for example those listed on the JSE but headquartered abroad such as Richemont which is based in Switzerland and British American Tobacco – and domestic companies with their primary listing on the JSE such as banks and retailers, which benefit from a stronger rand.
One indirect side effect of the JSE’s concentration is that South African pension funds also risk over-exposure to China.
Naspers and Prosus own large stakes – more than 22 per cent – in China’s Tencent while the large mining companies such as Glencore and Anglo American are heavily reliant on the Chinese market.
“This is handled as a bespoke, risk-controlled strategy rather than a one-size-fits-all approach, ensuring that total exposure remains within the fund's risk tolerance,” Kraushaar said.
Despite these issues, many South African pension funds are not using the 45 per cent offshore allowance because South African equity valuations have remained attractive.
There is also a strong strategic preference for investing domestically to align with the needs of members who will retire in the South African economy, Kraushaar added.
“Beyond listed equities, funds are increasingly using unlisted exposure—such as venture capital—to gain access to AI, technology, and biotechnology sectors that are underrepresented on the JSE,” Kraushaar said.
Investment decisions involve a balancing act between seeking offshore opportunities and fulfilling the mandate to invest in South African infrastructure for the benefit of domestic retirees, a strategy used by the largest South African pension fund, the $149bn Government Pensions Fund.