
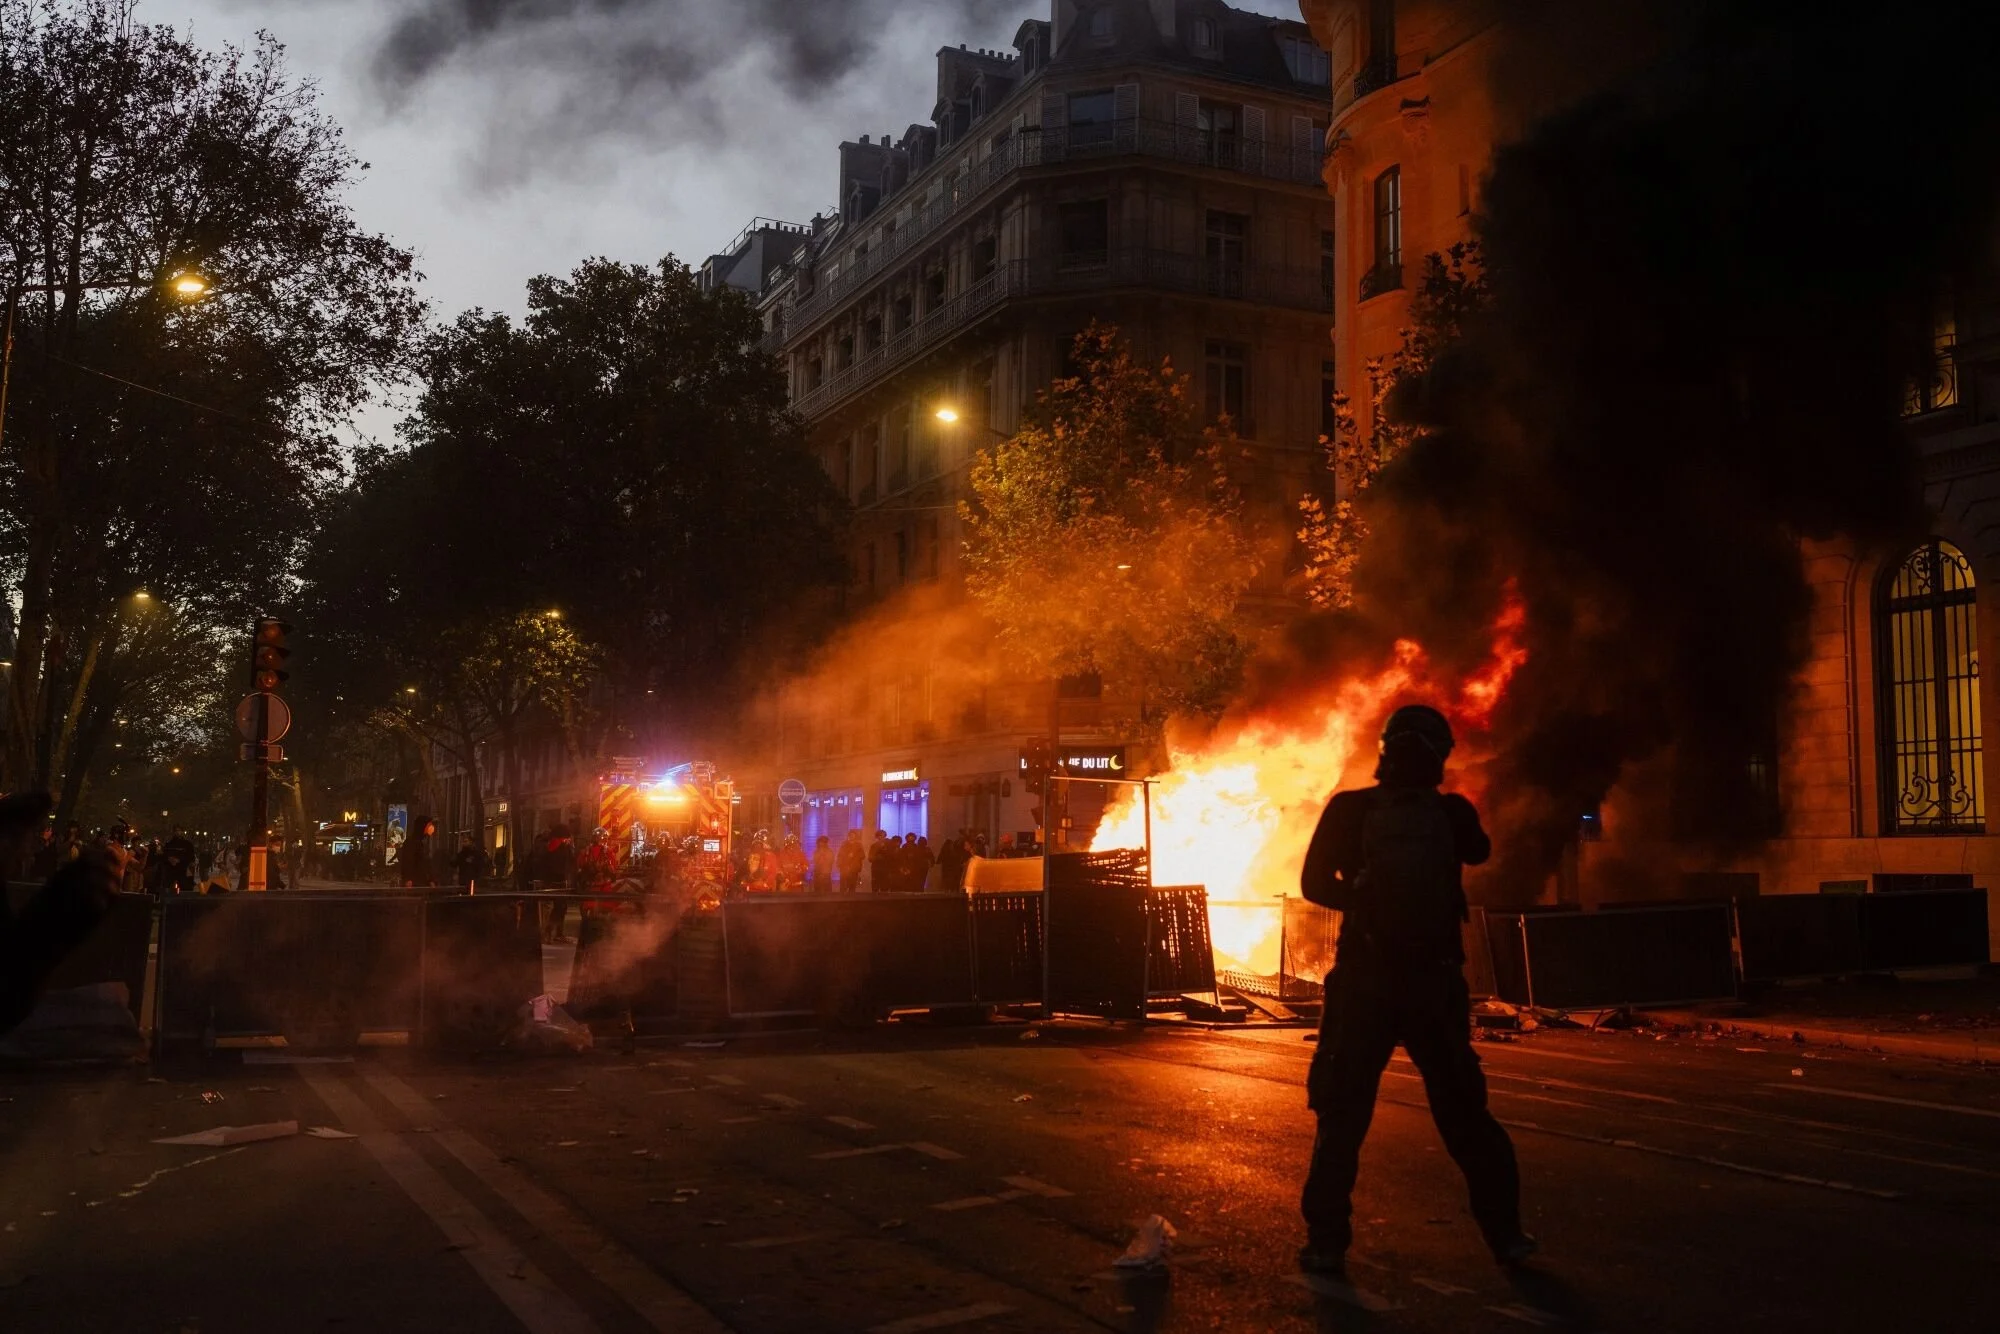
French government bond yields have hit a 24-year high after the wave of protests across France over the past few weeks. For asset owners, the increased cost of borrowing is a double-edged sword (Wayan Barre/Bloomberg)
Last week French government bond yields hit a 24-year record high. For the first time since 2002, yields on the 10-Year Obligation Assimilable du Trésor, or Oat, climbed above 5 per cent.
This adds to the increase seen before the summer but French borrowing costs were propelled to new peaks by worries about the lack of consensus for the country’s 2027 budget and growing civil discontent.
During October weeks of simmering unrest over a variety of issues spilled over into violent riots across the country making global headlines. The protests, which began in September led by students demanding better conditions in high schools amid concerns about budget cuts, transformed into a wider movement bringing together a range of causes including the cost of living, social inequality and housing affordability.
And as French citizens took to the streets, French government bond yields surged creating further headaches for the country’s leaders.
But for French asset owners the increased state borrowing rates are a double-edged sword.
At the beginning of the year many French pension funds and insurers expressed an appetite for allocations to domestic government bonds, seeking to benefit from the higher interest rate environment.
But recent turmoil is leading to some slightly more circumspect views.
Lyes Arezki, portfolio manager for the $15bn union pension fund UMR said the fund is aiming “to restore granularity and provide a ‘firebreak’ within our portfolios.”
He highlighted the exceptional volatility in interest rates, amid heightened uncertainty in an increasingly complex geopolitical and macroeconomic environment.
“I believe the key challenge for institutional investors is to manage sovereign risk exposure while preserving diversification and maintaining a risk-adjusted return profile consistent with their long-term commitments,” Arezki said.
Indeed for many French asset owners, geographic diversification is likely to become a focus amid concerns of a potential downgrade of France’s credit rating.
Meanwhile Arezki underlined the conundrum of balancing the risk-return profile of portfolios in the current context.
“When you’re in France and contributing toward your retirement, you expect a return that is at least better than the French risk-free rate,” Arezki said.