
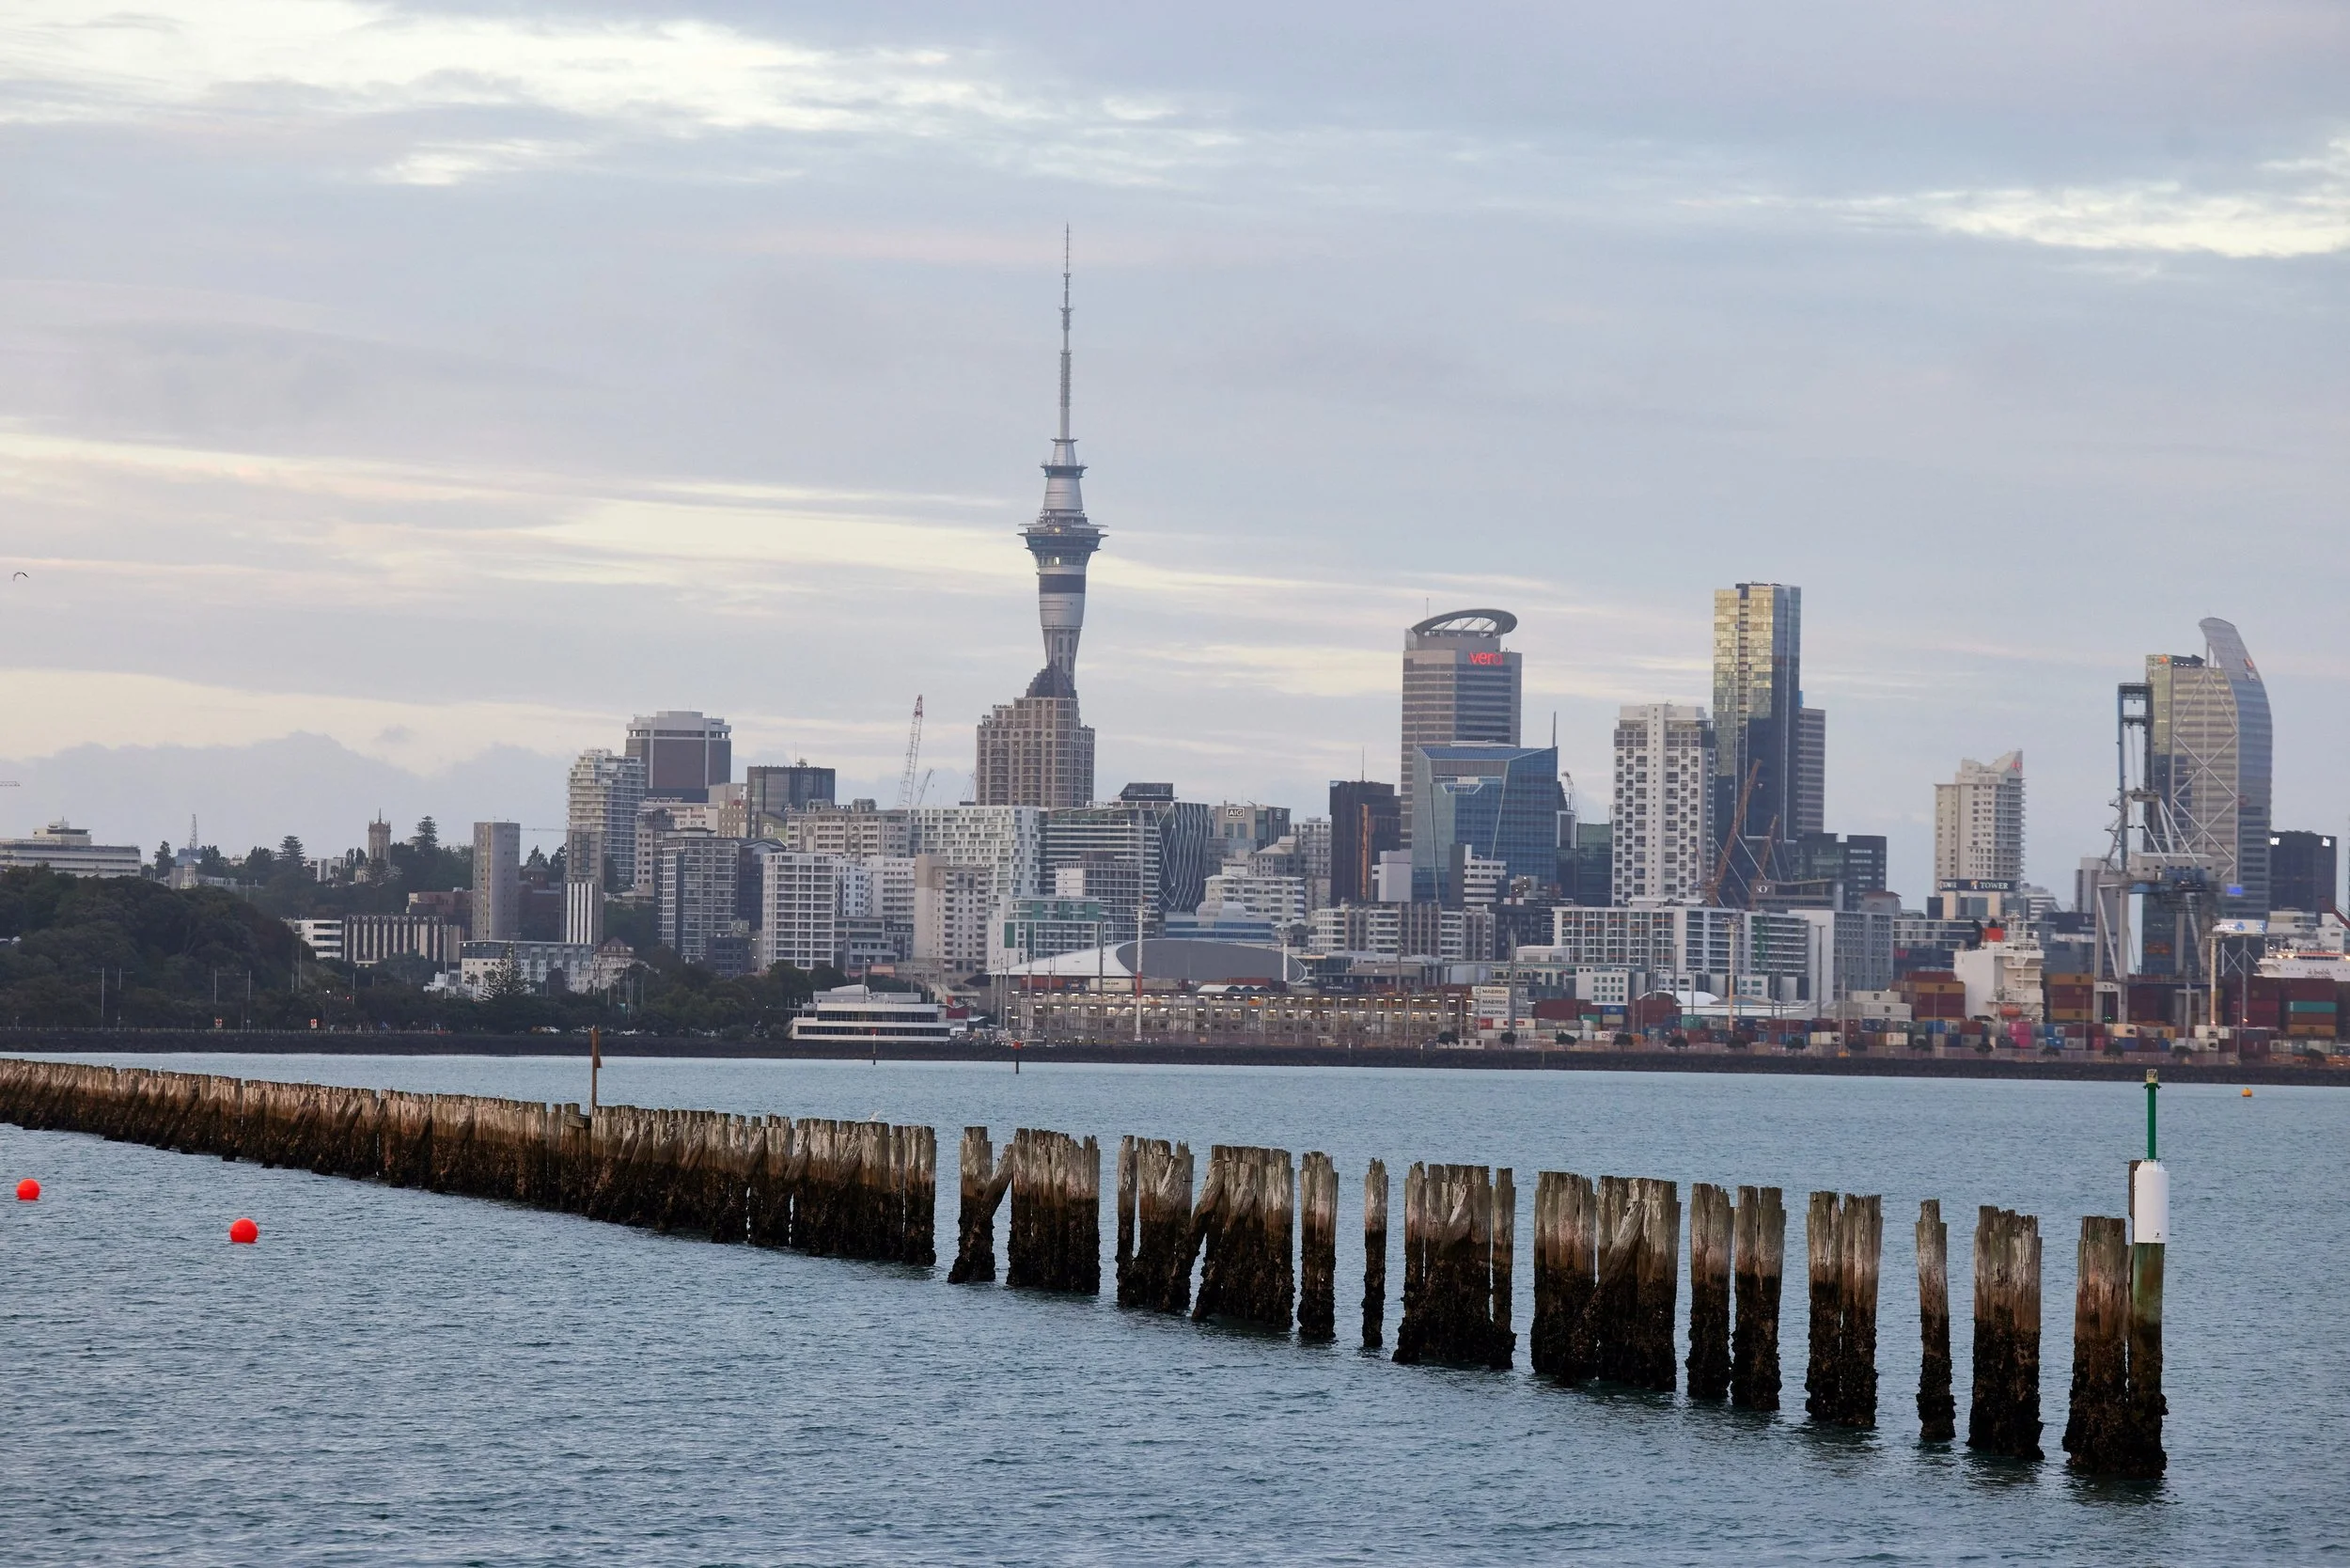
The $54bn NZ Super fund, which is based in Auckland, has been one of the pioneers of the total portfolio approach since 2010, but over the course of this year it has shaken up the way it runs its portfolio to become “more nimble” (Brendon O’Hagan/Bloomberg)
The $54.3bn NZ Super Fund has been practising some form of total portfolio approach since 2010 and has been refining its process with a recent restructure.
The fund, which is globally recognised as a TPA pioneer, lists the approach as one of its core beliefs, with a view that it enables a “flexible and dynamic approach to capital allocation” supported by a “high degree of collaboration across the investment team”.
But NZ Super has recently decided to change its approach to TPA.
Alex Bacchus, the fund’s head of asset allocation, tells AOX that during its latest fiscal year, NZ Super reorganised its teams by asset class. They had previously been grouped in an access point team structure that was based on how the fund enters investments, such as directly or through external managers.
As part of the restructure, the fund appointed Qing Ding to the newly created role of head of portfolio strategy and research in February. Bacchus says her duties include leading a team that works across asset classes to reduce silos and make comparisons easier.
“We have moved away from access point focussed teams as we want the primary competitive tension to be regarding which opportunity to invest in rather than how we access that investment. We think that this part of the investment decision is more important and gives us stronger returns,” he says.
The change also makes NZ Super more nimble, Bacchus says, giving the example of the real assets team, which covers real estate, rural land, infrastructure and forestry.
“If real estate was dialled down, the team would continue work on other asset classes in the group while keeping sufficient market coverage of real estate if needed in the future,” he says.
Measuring success
NZ Super’s TPA is based on a reference portfolio, a passive portfolio and benchmark comprising 75 per cent global equities, 20 per cent fixed income, and 5 per cent New Zealand equities. When NZ Super chooses to take active risk, it funds the opportunity by selling a risk-matched portion of its reference portfolio.
Alex Bacchus, NZ Super’s head of asset allocation, says the new approach will make the fund more “nimble”.
Since July the fund has expected the active investments it makes through its TPA to add 0.9 per cent a year over the reference portfolio, down from 1 per cent previously. So how has NZ Super done in terms of returns? In three of the last four years, the fund has underperformed its reference portfolio, including the year to June 30 2026, when it missed by 10 basis points. But over 10 years it is ahead by 1.54 per cent a year.
Meanwhile, NZ Super’s former chief investment officer Stephen Gilmore has introduced TPA to the $600bn Calpers, where he is now CIO, making it the first US public pension fund to implement the approach.
Like NZ Super, Calpers has also had to make organisational changes to support the shift.
Gilmore says that Derek Walker, who joined the fund from CPP Investments, another TPA practitioner, is “a very welcome addition”. Walker has been appointed managing investment director for total fund portfolio management.
But unlike NZ Super, Calpers’ teams were already organised by asset class before its shift to TPA. In a January 2025 presentation to Calpers’ board, Gilmore described the culture under SAA as “siloed”. He later told the board the fund was already paying its team on whole-portfolio results rather than by asset class.
Gilmore tells AOX that most of the hard work for Calpers’ transition took place well ahead of the July 1 deadline and that the likely gain from TPA is “keenly debated”.
“I have been on record as saying it would be reasonable for Calpers to expect a 50-60bp uplift over the reference portfolio over longer periods of time,” he says.
Calpers has selected a 75/25 equities and bonds benchmark to replace the 11 benchmarks previously used for each asset class. Citing a study of 26 large funds by the Thinking Ahead Institute and Australia’s Future Fund, Calpers says TPA users beat strategic asset allocation users by 1.3 per cent a year over a decade.
That 1.3 per cent comes with a caveat, though, as the study’s own authors say the test “may be crude”. They attribute much of the gap to TPA funds’ larger private-market allocations, better governance, and greater internalisation, but still conclude that TPA appears to be a significant performance factor.
Trusting the process
But not everyone is convinced that TPA can reliably add value to portfolios.
Keith Ambachtsheer, director emeritus of the Rotman School’s International Centre for Pension Management, sees TPA as the practical implementation of portfolio theory as set out by Harry Markowitz and William Sharpe.
“It can add value if implemented sensibly. Whether that is done or not is an empirical question. I have yet to see a study testing the ‘if implemented sensibly’ hypothesis,” he tells AOX.
Ambachtsheer questions whether the shorter-term trading strategies that operate under TPA can reasonably be expected to add even 10, 20, or 30 basis points to total fund returns without strong evidence of the predictive ability required to justify net value-added projections.
“Boards have to believe the investment team can generate positive correlations between return expectations and actual outcomes,” he tells AOX.
Both NZ Super’s and Calpers’ boards set their funds’ overall risk appetite and active risk budget, with the investment teams making decisions within these active risk limits.
For Gilmore, perhaps the biggest potential gains conceptually should come from “optimising the portfolio as a whole and sharing information across asset classes”, which could lead to investment opportunities that lie outside of the traditional SAA buckets.
Bacchus says TPA can be difficult because funds require “appropriate incentives” to drive collaboration across teams.
“You need to make sure that people are incentivised by total fund performance, for example, rather than individual asset performance or even asset class performance,” he says.
TPA can make performance simpler to judge because one reference portfolio replaces multiple benchmarks. But identifying the sources of outperformance still requires detailed attribution, as shown in NZ Super’s annual reports.
Although the debate around TPA is still very much a live one, Bacchus says it needn’t be an all-or-nothing situation.
“Even with an SAA starting point you can still consider the total portfolio. There’s definitely some components you can run on a TPA-style approach,” he says.